HDFC Millennia Review 2026: 5% Cashback Partners, 1% Base, Caps & FAQs
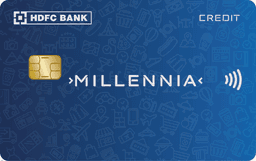
HDFC Millennia earns 1 CashPoint per ₹1 at ₹1 — a 1% base — with 5% at Amazon, Flipkart, Swiggy, Zomato and more, and 10% on SmartBuy and PayZapp. Redemption caps, fees and FAQs.
Millennia is HDFC's best-known cashback card and the sensible default for online spending at ₹1,000 a year. A 1% base with 5% at ten major online merchants and 10% on SmartBuy and PayZapp is a strong offer at that fee.
The number that decides whether it works for you is not any of those rates. It is the 3,000-CashPoint monthly redemption cap.
HDFC Bank Millennia Credit Card Quick Overview
| **Card type** | Entry-to-mid cashback card |
|---|---|
| **Best for** | Online shoppers who spend across Amazon, Flipkart, Swiggy and Zomato |
| **Joining / renewal fee** | ₹1,000 + GST, same on renewal — renewal waived at ₹1 lakh of annual spend |
| **Network** | Visa, Mastercard |
| **Base reward rate** | **1.0%** |
| **Top reward rate** | **10.0%** — SmartBuy and PayZapp |
| **Reward currency** | CashPoints, valued at ₹1 each |
| **Lounge access** | 1 domestic visit per quarter (4 a year) |
| **Forex markup** | 3.5% |
Reward Structure: How You Earn
Millennia earns CashPoints, worth ₹1 each against your statement — which makes every rate below a true cashback percentage rather than a points figure needing translation.
5% at Amazon, Flipkart, Myntra, Tata CLiQ, Swiggy, Zomato, Uber, BookMyShow and Sony LIV. 10% on SmartBuy and PayZapp. 1% on everything else.
This card was not affected by HDFC's 15 May 2026 rate change. The cashback co-brands and CashPoints cards were named on the unchanged list; only the Reward Point cards moved from ₹150 to ₹200 earning blocks.
| Spend | Effective rate |
|---|---|
| SmartBuy and PayZapp | **10.0%** |
| Amazon, Flipkart, Myntra, Tata CLiQ, Swiggy, Zomato, Uber, BookMyShow, Sony LIV and Cult.fit | **5.0%** |
| Everything else | 1.0% |
| Fuel, rent, wallet loads, government, gaming | **0%** |
The caps that actually bind
Headline rates mean little until you know where they stop. These are the limits on this card:
| Cap | Limit |
|---|---|
| Cashback Redeem | 3,000 points per calendar month |
Cashback redemption is capped at 3,000 CashPoints a statement cycle. You can earn more than that, but you can only convert 3,000 points to statement credit per cycle — the rest waits. On a card sold as cashback, that is a meaningful constraint most holders discover late.
At 5% you reach 3,000 CashPoints on ₹60,000 of partner spending in a cycle. Beyond that you are still earning, but the redemption queue builds.
Worked example
₹45,000 a month, online-weighted.
| Category | Monthly spend | Rate | Cashback |
|---|---|---|---|
| SmartBuy and PayZapp | ₹5,000 | 10% | ₹500 |
| Amazon, Flipkart, Swiggy, Zomato | ₹20,000 | 5% | ₹1,000 |
| Other retail | ₹17,000 | 1% | ₹170 |
| Fuel | ₹3,000 | 0% | ₹0 |
| **Monthly total** | **₹45,000** | **₹1,670** |
₹1,670 a month is ₹20,040 a year against a ₹1,000 fee that is reversed anyway at ₹1 lakh of spend. But only 3,000 CashPoints a cycle can actually be redeemed — this pattern earns 1,670, so it stays comfortably inside the cap.
Milestone Benefits
| Spend | Benefit | Value |
|---|---|---|
| ₹1 lakh a quarter | ₹1,000 gift voucher OR 1 domestic lounge access | ₹1,000 |
Category Restrictions: Where You Won't Earn
- Where you earn nothing: Earns nothing at all: fuel; EasyEMI and e-wallet loading; rent, property management, maintenance and packers-and-movers; government transactions; education paid through third-party apps such as CRED, Cheq or MobiKwik (paying a college or school directly still earns); and online skill-based gaming. Points are also REVERSED if a retail transaction is later converted to SmartEMI.
- Point expiry: Reward Points are valid for 24 months from accrual and lapse thereafter — HDFC states 'Unredeemed Reward Points will expire/lapse after 2 years of accumulation'.
- Redemption fee: ₹99 per redemption.
- Cashback Redeem cap: 3,000 CashPoints per calendar month on statement-credit redemption, w.e.f. 1 February 2023 — ₹3,000 a month. This is a REDEMPTION cap, not an earning cap: points accrue beyond it but cannot be cashed out in the same month. A minimum of 500 CashPoints is required for statement redemption.
Fees and Charges
| Charge | Amount |
|---|---|
| Joining fee | ₹1,000 + GST |
| Renewal fee | ₹1,000 + GST |
| Finance charges | Up to 3.75% per month (45% per annum). The rate applied depends on the card variant and the cardholder's profile. |
| Interest-free period | Up to 50 days, and only if the previous month's balance was cleared in full. No interest-free period applies once a balance is revolved or a cash advance taken. |
| Minimum amount due | 5% of the total outstanding, or the sum of 100% of EMI, fees, charges, interest and any overlimit amount plus 1% of the principal — whichever is higher. Subject to a minimum of ₹200. |
| Cash advance fee | 2.5% of the amount withdrawn, subject to a minimum of ₹500. |
| Cash advance interest | Up to 3.75% per month, charged from the date of withdrawal until repayment in full. |
| Forex markup | 3.5% on the INR-converted amount for most variants; premium variants carry 2%. |
| Dynamic currency conversion | 1.75% markup on transactions made in Indian rupees at an international merchant or an overseas-registered merchant, with effect from 15 May 2026. |
| Late payment | Nil up to ₹100; ₹100 for ₹101–₹500; ₹500 for ₹501–₹1,000; ₹600 for ₹1,001–₹5,000; ₹800 for ₹5,001–₹10,000; ₹1,100 for ₹10,001–₹25,000; ₹1,300 for ₹25,001–₹50,000; ₹1,300 above ₹50,000. |
| Overlimit | 2.5% of the overlimit amount, subject to a minimum of ₹550. |
| Payment return | 2% of the payment amount, subject to a minimum of ₹450. |
| Rent payment | 1% of the transaction amount on rent payments made through third-party merchants, levied FROM THE SECOND rental transaction of the calendar month — so the first rent payment each month is free of it. Rent and property-management transactions also earn no Reward Points at all, w.e.f. 1 January 2023. |
| Wallet load | 1% on wallet-loading spends exceeding ₹10,000 in a calendar month, excluding PayZapp, with effect from 1 October 2025. The fee applies to the total wallet-loading spend for the month, capped at ₹4,999. |
| Utility payments | 1% on utility spends exceeding ₹50,000 in a calendar month for consumer cards (₹75,000 for business cards), with effect from 1 October 2025. The fee applies to the total utility spend for the month, capped at ₹4,999. |
| Education payments | 1% on education transactions made through third-party applications such as CRED, NoBroker or Cheq, capped at ₹4,999 per transaction. Education paid DIRECTLY through a college or school website, or at its POS machine, attracts no fee. |
| Fuel transactions | 1% on fuel transactions exceeding ₹15,000 for consumer cards (₹30,000 for business cards), with effect from 1 October 2025. The fee applies to the total transacted amount, capped at ₹4,999 per transaction. |
| Online skill-based gaming | 1% on online skill-based gaming spends exceeding ₹10,000 in a calendar month, with effect from 1 October 2025, applied to the month's total and capped at ₹4,999. |
| Card replacement | ₹100 plus taxes. |
| Add-on card | Nil. |
| Reward redemption | ₹99 plus taxes on redemption through the rewards catalogue. |
| EMI processing | ₹199 plus taxes on retail EMI conversion. |
| GST | 18% on all fees, interest and charges. |
Is the HDFC Bank Millennia Credit Card Worth It?
At ₹1,000 with a ₹1 lakh reversal threshold, Millennia is easy to justify for anyone whose spending is meaningfully online. ₹20,000 a month across the 5% partners returns ₹1,000 a month — the fee back in the first month of the year.
The 10% SmartBuy and PayZapp rate is the headline and the least reliable part. PayZapp routing and SmartBuy availability both change, and HDFC has narrowed SmartBuy repeatedly across its range.
The redemption cap is the real limit. 3,000 CashPoints a cycle means a practical ceiling of ₹36,000 a year of realisable cashback regardless of how much you earn.
Against MoneyBack+ at half the fee, Millennia earns four times the base rate and has a much better partner list. The extra ₹500 is well spent.
Frequently Asked Questions (FAQs)
What is the HDFC Millennia fee? ₹1,000 plus GST on joining and renewal, reversed at ₹1 lakh of annual spend — a threshold most regular users clear.
Which merchants earn 5% on Millennia? Amazon, Flipkart, Myntra, Tata CLiQ, Swiggy, Zomato, Uber, BookMyShow and Sony LIV.
Is a CashPoint worth ₹1? Yes, against your statement balance — which is what makes Millennia a genuine cashback card rather than a points card. Redeeming for catalogue products pays far less.
What is the cashback cap? 3,000 CashPoints per statement cycle can be redeemed as statement credit. You can earn beyond it, but not convert beyond it in the same cycle.
Did Millennia change in May 2026? No. The 15 May 2026 block change applied to HDFC's Reward Point cards; the cashback co-brands including Millennia were unchanged.
What does Millennia not earn on? Fuel, rent, wallet loads, government payments, third-party education apps and online gaming earn nothing, and points are reversed if a purchase is converted to SmartEMI.
Cards Mentioned in This Article