CASHBACK SBI Card Review 2026: 5% on All Online Spends, the ₹5,000 Cap, Exclusions & FAQs
CASHBACK SBI Card costs ₹999 and pays a flat 5% on every online spend with no merchant restriction, 1% offline, capped at ₹5,000 a month. Full cashback maths, the long exclusion list, fees and FAQs.
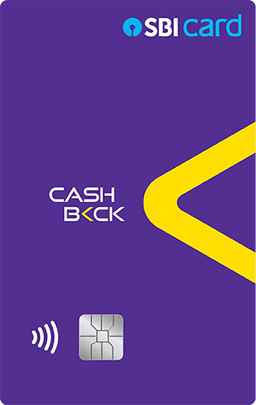
The CASHBACK SBI Card does one thing, and it does it better than almost anything else in the Indian market: 5% cashback on every online spend, with no merchant restriction. Not 5% at a named partner list. Not 5% on selected categories. Five per cent on anything the card networks flag as an online transaction. It costs ₹999, the fee is reversed at ₹2 lakh of annual spend, and the whole benefit is capped at ₹5,000 a month.
There is no welcome bonus, no lounge access, no insurance and no milestone programme. It is a single-mechanic product, and the mechanic is a good one.
CASHBACK SBI Card Quick Overview
| **Card type** | Flat-rate cashback card |
|---|---|
| **Best for** | Anyone whose spending is mostly online |
| **Joining / annual fee** | ₹999 + GST, same on renewal — reversed at ₹2,00,000 of annual spend |
| **Network** | Visa, Mastercard or RuPay |
| **Online rate** | **5%** — no merchant restriction |
| **Offline rate** | **1%** |
| **Monthly cap** | ₹5,000 of cashback, shared across both rates |
| **Reward type** | Cashback, auto-credited — worth ₹1 per ₹1, no conversion |
| **Welcome benefit** | None |
| **Lounge access** | None |
Eligibility Criteria
SBI Card publishes no age or income threshold for this card. Approval rests on the bank's own assessment of income, credit history and internal scoring. Indian residency and a valid PAN are required. Add-on cards are free.
The 5% Is Real — Here Is Exactly How It Works
Most "5% cashback" cards in India narrow the rate to a partner list or a category. SBI's wording here is deliberately broad: 5% on online spends, full stop.
The determination is made by channel, not by merchant category. SBI identifies an online spend from the card-not-present indicators the card networks and the acquirer send with the transaction, and its T&C states plainly that "any transaction not categorized as online would be termed as offline". In practice that means:
- Shopping on any e-commerce site — 5%
- Paying a merchant's own website directly — 5%
- In-app purchases on a merchant app — 5%
- Swiping or tapping at a physical store — 1%
- A QR-code payment at a shop counter — usually 1%, because it is flagged card-present
The practical consequence is that eligibility depends on how the acquirer flags the transaction, not on what you bought. An online merchant whose payment gateway sends a card-present flag will earn 1%. This is rare but not impossible, and it is worth spot-checking your statement in the first month or two.
The ₹5,000 Cap Is the Number That Governs Everything
Cashback is capped at ₹5,000 per statement cycle, shared across both rates. It is not ₹5,000 on online and another ₹5,000 offline — it is one pool.
| Monthly online spend | Cashback | Effective rate |
|---|---|---|
| ₹20,000 | ₹1,000 | **5%** |
| ₹50,000 | ₹2,500 | **5%** |
| ₹1,00,000 | ₹5,000 | **5%** |
| ₹1,50,000 | ₹5,000 (capped) | 3.3% |
| ₹2,00,000 | ₹5,000 (capped) | 2.5% |
The cap binds at ₹1,00,000 of online spend in a cycle — or ₹5,00,000 of offline spend, or any combination reaching ₹5,000 of cashback.
Past the cap, SBI publishes no fallback rate. The conservative reading, used throughout this article, is that further spend earns nothing for the rest of the cycle. If your online spend regularly exceeds ₹1 lakh a month, a second card for the overflow is worth having.
At the cap sustained, the card returns ₹60,000 a year against a ₹999 fee that is itself reversed at ₹2 lakh of spend. That is the best flat-rate return available on an Indian credit card.
The Exclusion List — Read This Before Applying
This is the card's real fine print, and it is longer than most. None of the following earns cashback at any rate, online or offline:
| Excluded | MCCs |
|---|---|
| **Fuel** | 5172, 5541, 5542, 5983 |
| **Wallet loads** | 6540, 6541 |
| **Rent and property management** | 6513, 7349 |
| **Jewellery** | 5051, 5094, 5944, 7631 |
| **Education** | 5111, 5192, 5942, 5943, 8211, 8220, 8241, 8244, 8249, 8299, 8351 |
| **Utilities** | 4814, 4816, 4899, 4900, 9399 |
| **Insurance** | 5960, 6300, 6381 |
| **Gift and novelty shops** | 5947 |
| **Railways** | 4011, 4112 |
| **Quasi-cash** | 6011, 6012, 6051 |
| **Cash advances, balance transfers, Flexipay** | — |
These codes are published in SBI's own T&C e-kit, not inferred.
The exclusions matter more than they look, because several of them are exactly the things people pay online. Utility bills, insurance premiums, school and college fees, and rent are all common online payments and all earn nothing here. Neither does railway ticketing. If a large share of your online spending is bills rather than shopping, the effective rate on this card will be well below 5%.
EMI is also excluded, and the T&C's own example proves it. SBI illustrates ₹35,000 of online spend including a ₹10,000 EMI purchase, plus ₹10,000 offline: the result is 5% on ₹25,000 and 1% on ₹10,000 — the EMI slice earns nothing. And cashback already credited on a transaction that is later converted to EMI is reversed.
How the Cashback Reaches You
Auto-credited to your card account within two working days of the next statement generation. There is no redemption step, no minimum, no catalogue, no redemption fee and no expiry. The cashback simply reduces your outstanding.
This is the cleanest redemption mechanic in SBI's range. Every other card in the range earns Reward Points worth ₹0.25 each, redeemed through a catalogue, with a ₹99 fee on physical redemptions. Here, ₹1 of cashback is ₹1.
Worked Example
Illustrative, at ₹55,000 a month:
| Category | Monthly spend | Rate | Cashback |
|---|---|---|---|
| Online shopping (e-commerce, apps) | ₹28,000 | 5% | ₹1,400 |
| Offline retail and dining | ₹15,000 | 1% | ₹150 |
| Utility bills and insurance | ₹8,000 | **0%** | ₹0 |
| Fuel | ₹4,000 | **0%** | ₹0 |
| **Monthly total** | **₹55,000** | **₹1,550 — 2.8%** |
Annualised: ₹18,600 on ₹6.6 lakh of spend, against a ₹999 fee reversed at ₹2 lakh — cleared three times over.
Note how the excluded categories drag the headline down. On the ₹28,000 that qualifies for 5%, the card performs perfectly; across total spend the blended rate is 2.8%. That is still excellent, but it is not 5%.
Fees and Charges
| Charge | Amount |
|---|---|
| Joining fee | ₹999 + GST |
| Renewal fee | ₹999 + GST, reversed at ₹2,00,000 annual spend |
| Add-on card fee | Nil |
| Finance charge | 3.75% per month — **45% per annum** |
| Interest-free period | 20 to 50 days; none if any part of last month's bill is unpaid |
| Forex markup | 3.5% |
| Cash advance fee | 2.5%, minimum ₹500 |
| Fuel surcharge waiver | 1% on ₹500–₹3,000, max ₹100 per cycle |
| Rent payment fee | ₹199 per transaction |
| Wallet load fee | 1% above ₹1,000 |
| Utility payment fee | 1% when the cycle total exceeds ₹50,000 |
| Education payment fee | 1% via third-party apps |
| Late payment | ₹100 to ₹1,300 by balance |
| Overlimit | 2.5%, minimum ₹600 |
| GST | 18% on all of the above |
Note the double hit on some categories: rent, wallet loads, utilities and third-party education payments are *excluded from cashback and carry their own transaction fee*. Paying ₹60,000 of utilities in a cycle on this card costs you ₹600 in fees and earns you nothing.
CASHBACK SBI Card vs SimplyCLICK
Both are online-leaning cards, and the comparison is worth making.
| **CASHBACK SBI Card** | SimplyCLICK SBI Card | |
|---|---|---|
| Annual fee | ₹999 | ₹499 |
| Fee reversal | ₹2,00,000 | ₹1,00,000 |
| Top online rate | **5% on everything online** | 2.5%, partner merchants only |
| Other online | 5% | 1.25% |
| Offline | 1% | 0.25% |
| Cap | ₹5,000 / month | None published |
| Milestones | None | ₹4,000 of vouchers |
| Reward currency | **Cashback (₹1 = ₹1)** | Reward Points (₹0.25 each) |
Unless your online spending is concentrated entirely on SimplyCLICK's eleven partner merchants and stays under roughly ₹1.5 lakh a year, the CASHBACK card wins comfortably. The extra ₹500 of fee buys double the rate on a far wider base, and cashback at face value beats points at ₹0.25.
Is the CASHBACK SBI Card Worth It?
Yes, for most people who shop online. At ₹999, reversed at ₹2 lakh of annual spend, paying 5% on unrestricted online transactions, this is among the strongest value propositions on any Indian credit card. If you spend ₹20,000 a month online you take ₹12,000 a year.
Yes, as a second card alongside a travel or fuel card. It has no lounge access, no insurance and no milestones — it is purely an earning engine, and it pairs well with a card that has the perks.
Less compelling if your online spending is mostly bills. Utilities, insurance, rent, education and railways are all excluded, and several carry transaction fees on top. Check your last three months of online spend against the exclusion list before applying.
Not the right card if you want a single do-everything card. There is no travel benefit of any kind here.
Frequently Asked Questions
What is the annual fee of the CASHBACK SBI Card? ₹999 plus GST, on joining and renewal. The renewal fee is reversed if annual spend in the previous year reached ₹2,00,000. The joining fee is not reversible.
Is the 5% cashback really on all online spends? Yes, with no merchant restriction — that is the card's defining feature. The limits are the excluded categories (fuel, wallet loads, rent, jewellery, education, utilities, insurance, gift shops, railways, quasi-cash) and the ₹5,000 monthly cap.
What is the monthly cashback cap? ₹5,000 per statement cycle, shared across the 5% online and 1% offline rates. It binds at ₹1,00,000 of online spend. SBI publishes no fallback rate past the cap, so treat further spend as earning nothing that cycle.
How and when is cashback credited? Automatically to your card account within two working days of the next statement generation. No redemption step, no minimum, no catalogue, no fee and no expiry.
Do EMI transactions earn cashback? No. SBI's own T&C example shows an EMI purchase within an online transaction earning nothing. Cashback already credited on a transaction later converted to EMI is reversed.
Does the card earn on fuel? No. Fuel is excluded from the cashback programme, as on every SBI card. The 1% fuel surcharge waiver (₹500–₹3,000, max ₹100 a cycle) is the entire fuel benefit.
Does it come with lounge access or insurance? No. The CASHBACK SBI Card has no lounge programme, no insurance and no milestone benefits. It is a single-mechanic cashback card.
Is there a welcome bonus? No. SBI publishes no welcome benefit for this card.
Cards Mentioned in This Article