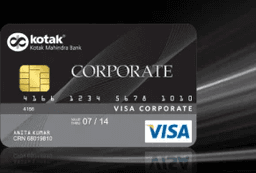
Kotak Corporate Platinum Credit Card Review 2026: 2 Lounge Visits a Quarter, Travel Insurance, Fees
The Kotak Corporate Platinum is the upper tier of Kotak's corporate travel-and-entertainment range: nil joining fee, ₹999 a year, and the one thing its Gold sibling does not publish — 2 complimentary domestic airport lounge accesses per calendar quarter, with no spend gate.
As with every card in Kotak's corporate range, the reward rate is not published. The page says "Earn higher Reward Points" and "earn high rewards points every time you transact", and never puts a number to it. The corporate MITC explains why: the incentive is negotiated with each company individually. Treat the earn rate as something your relationship manager quotes, not something you can compare.
Kotak Corporate Platinum Quick Overview
| **Card type** | Corporate travel-and-entertainment card |
|---|---|
| **Best for** | Companies whose employees fly domestically and need lounge access plus expense control |
| **Joining fee** | Nil |
| **Annual fee** | ₹999 + GST. **No waiver in either year** |
| **Network** | Visa |
| **Reward rate** | **Not published** — negotiated per corporate under the Incentive Program |
| **Domestic lounge** | **2 per calendar quarter**, primary cardholder only, no spend gate |
| **Interest** | 3.30% per month (39.60% per annum) on the corporate-liability variant |
| **Minimum amount due** | **20%** of the statement outstanding |
| **Cash withdrawal** | Not active on this card |
| **Insurance** | 7 covers, ₹50,000 card liability + six travel covers of ₹10,000 |
Airport Lounge Access — the reason to pick this over the Gold
2 accesses per calendar quarter, for the primary cardholder only, under the Visa airport lounge programme.
What makes this notable is not the number but the absence of a condition. Kotak's lounge terms put several of its cards behind a previous-quarter spend gate — ₹75,000 on the Kotak Biz, ₹60,000 on the Kotak Air, ₹1,00,000 on the White — and the corporate range appears in none of those groups. Access here looks unconditional, which for an employee card is exactly right: you do not want a salesperson's lounge access depending on last quarter's expense volume.
Eight visits a year, at a realistic ₹1,000 a visit, is roughly ₹8,000 of value against a ₹999 fee.
A ₹2 validation charge applies per visit. No international lounge access — Kotak's Priority Pass list covers the Corporate Wealth Signature card, not the Corporate Platinum.
Rewards: what is and isn't known
What the page states:
- "Earn higher Reward Points"
- Points redeemable every quarter, by calling the customer service desk
- Cash rebate given through a demand draft
What the corporate MITC adds:
- Clause 7.1: the Incentive Program is offered "at the exclusive discretion of the Kotak Bank, and may vary from Card to Card", with the accrual rate and qualifying spends communicated to the corporate by a Commercial Card Relationship Manager by email
- Clause 7.3.13: the incentive is paid to the corporate by funds transfer, NEFT or RTGS
- Clause 7.3.21: reward points expire two years from the date earned, with no prior intimation (business card customers get an SMS five days before)
What is never stated: points per ₹100, the rupee value of a point, accelerated categories, caps, or any MCC exclusion list.
The incentive can be taken away
Conditions with no parallel on a retail card:
- Forfeited if the corporate has a delinquent card account at the start of the programme or during it
- Not paid for a year in which the Commercial Card Program is not renewed
- Nullified if Kotak closes the programme or the card account
- Clause 7.3.10: if the client does not upload invoices and Kotak cannot claim input credit, the bank may recover from future incentive or close the cards
And the incentive goes to the company. An employee who routes personal spend through this card to chase points is earning for their employer.
Liability variants change the economics
This is easy to miss. Kotak issues the Corporate Platinum in three liability structures, and the corporate MITC prices them differently:
| Variant | Liability | Annual fee | Interest |
|---|---|---|---|
| CCCL | Corporate | ₹999 | 3.30% / month (39.60% p.a.) |
| CCIL | Individual | Nil | **3.50% / month (42.00% p.a.)**, plus a ₹300 charge |
| CCJ&SL | Joint and several | Nil | 3.30% / month (39.60% p.a.) |
This review uses the paid CCCL figures. Which variant you get depends on the liability structure your company chose, and no public page states it.
Both surcharge waivers are flagged on the card page as applicable only on the paid annual fee variant. So if your company is on a nil-fee CCIL or CCJ&SL variant, you lose the fuel and railway waivers — and on CCIL you also pay the higher interest rate. Ask which one you are on.
Surcharge Waivers
Fuel: 1% waived on transactions between ₹500 and ₹3,000, capped at ₹3,500 in a calendar year, at petrol pumps across India. Paid annual fee variant only.
Railway: 1.8% waived on bookings at irctc.co.in and 2.5% at Indian Railways booking counters, capped at ₹500 in a calendar year. Paid annual fee variant only.
What the card actually does
Past the lounge and the waivers, this is an expense-management product:
One limit, divided by you. A single company limit is assigned and the corporate decides each employee's share — by hierarchy, by designation, or however it chooses.
Consolidated billing. One payment covers every employee card. No employee pays anything or chases a reimbursement.
Spend analytics. Employee-wise and vendor-wise tracking, with data you can pull to see who spent what and where, and budget against it.
Real-time alerts. Free SMS and email alerts on every transaction.
A dedicated service manager and a Program Administrator acting as the single point of contact for due dates, totals, and lost or damaged cards.
No forex to carry. Employees travelling abroad use the card rather than drawing currency, and keep no vouchers for reimbursement purposes.
Fees and Charges
| Charge | Amount |
|---|---|
| Joining fee | Nil |
| Annual fee | ₹999 + GST — **no waiver in either year** |
| Add-on card fee | Not applicable |
| Finance charges | **3.30% per month (39.60% per annum)** on the corporate-liability variant |
| Interest-free period | Up to 48 days |
| **Minimum amount due** | **20% of the statement outstanding** |
| **Cash withdrawal** | **Not active** — ATM withdrawal, call-a-draft, fund transfer and cash advance all show NA |
| Forex markup | 3.50% |
| Late payment | ₹100 up to ₹500 outstanding; ₹500 from ₹500.01 to ₹10,000; ₹700 above ₹10,000 |
| Over-limit charge | Nil on corporate-liability cards; **₹500 on individual-liability corporate cards** |
| Cheque bounce | ₹500 |
| Cash payment at branch | ₹100 |
| Card reissue / replacement | **Waived** |
| Duplicate statement | **Waived** |
| Charge slip request | **Waived** |
| Outstation cheque processing | **Waived** |
| ATM machine surcharge | **Waived** |
| Balance enquiry at non-parent ATM | **Waived** |
| WebPay service fee | **Waived** |
| GST | Charged at the rates approved in the Finance Act on all interest, fees and charges |
The 39.60% interest is better than Kotak's 45% retail norm, though on a card settled in full each month it rarely matters.
The 20% minimum amount due is far steeper than the 1%-plus-charges formula on retail cards. On a corporate-liability card the company clears the balance and it never bites; on an individual-liability variant it is a serious monthly obligation.
The waived-fee list is long and genuinely useful at scale. Card replacement, duplicate statements, charge-slip retrieval, outstation cheques, ATM machine surcharge, non-parent-bank balance enquiry and WebPay are all free. Across a fleet of employee cards those charges would otherwise add up.
Note what the corporate fees schedule does not list: the special-category fees Kotak charges retail cardholders on rent, wallet loading, utilities, education, government payments, fuel, transport and online gaming. Their absence fits a business travel card rather than a household one, but it is an absence of information rather than a confirmed absence of charge.
Insurance
Seven covers, underwritten by Zurich Kotak Mahindra General Insurance, and the corporate MITC confirms all three Corporate Platinum liability variants are covered:
| Cover | Sum insured |
|---|---|
| Card liability — lost card, counterfeit, skimming, phishing, online fraud | ₹50,000 |
| Flight delay of more than 6 hours | ₹10,000 |
| Carrier cancellation | ₹10,000 |
| Loss of checked-in baggage | ₹10,000 |
| Delay of checked-in baggage | ₹10,000 |
| Valuable documents cover | ₹10,000 |
| Missing a connecting international flight during transit | ₹10,000 |
Conditions: primary cardholder only; the card must have had at least one ATM, POS or e-commerce transaction in the 90 days before the loss; claim documents due within 60 days of intimation. General exclusions for gross negligence, deliberate breach of law and terrorism.
For a card whose employees are flying, six travel covers plus ₹50,000 of fraud protection is a real benefit — and one the company does not have to buy separately.
Corporate Platinum vs Corporate Gold
| Corporate Platinum | Corporate Gold (Classic / Basic) | |
|---|---|---|
| Joining fee | Nil | Nil |
| Annual fee | ₹999 | ₹1,000 (Classic) / Nil (Basic) |
| Domestic lounge | **2 per calendar quarter** | Not published |
| Fuel waiver | ₹500–₹3,000, ₹3,500/year (paid variant) | ₹500–₹3,000, ₹3,500/year (Classic only) |
| Railway waiver | 1.8% / 2.5%, ₹500/year (paid variant) | Waived, ₹500/year |
| Interest | 39.60% (CCCL) | 39.60% |
| Insurance | Same 7 covers | Same 7 covers |
| Reward rate | Not published | Not published |
For essentially the same annual fee, the Platinum adds published lounge access and the Gold does not. Unless your company is being offered the free Corporate Basic variant, the Platinum is the better card — and even then, eight lounge visits a year is worth more than ₹999.
Note also that the Gold page has a naming problem the Platinum does not: its fees table is headed "Corporate Classic" and "Corporate Basic" with no Gold column at all.
How employees use it
- The card is meant for official expenses. Personal spend is allowed if company policy permits, but it appears on the consolidated corporate bill and must be settled with your employer.
- You do not pay the bill. No late payment worries, no reimbursement claims.
- Cash withdrawal is not active, so there is no cash advance facility to misuse.
- The card is valid internationally at Visa merchants worldwide.
How to apply
Not through a website form. Kotak's FAQ directs companies to email the bank with the entity name, a contact person, contact details and the number of cards required. A sales representative then follows up.
Who Should Get the Kotak Corporate Platinum Credit Card
Good fit if:
- Your employees fly domestically on business and would use eight lounge visits a year
- You want consolidated billing and employee-level spend visibility rather than a reimbursement process
- You value the travel insurance cover being bundled rather than bought
- You are issuing a fleet of cards and want the service fees to be zero
- You are prepared to negotiate the incentive terms rather than read them off a page
Look elsewhere if:
- You want a published, comparable reward rate — there isn't one on any Kotak corporate card
- Your company will be placed on a nil-fee liability variant — you lose both surcharge waivers, and on CCIL you pay 42% interest
- Your employees fly internationally and need lounge access abroad — that is the Corporate Wealth Signature card
- You are an individual or a proprietor looking for a business card — the Kotak Biz is the self-employed product, and it publishes its rates
Frequently Asked Questions
Is this card for individuals? No. It is issued to companies, which assign limits to employees. Applications go through a corporate relationship, not an online form.
What is the fee? Nil joining and ₹999 annual plus GST on the corporate-liability variant. There is no waiver condition in either the first or second year. Some liability variants carry no annual fee but lose the surcharge waivers.
How much lounge access do I get? 2 complimentary domestic airport lounge accesses per calendar quarter, primary cardholder only, under the Visa lounge programme. Unlike several Kotak retail cards, there is no previous-quarter spend requirement.
Is there international lounge access? No. Kotak's Priority Pass list covers the Corporate Wealth Signature card, not the Corporate Platinum.
How many reward points does it earn? Not published. The corporate MITC says the Incentive Program is set per corporate at the bank's discretion and communicated by a relationship manager by email. Ask for the rate in writing.
Who receives the rewards? The corporate, not the employee. Redemption is arranged quarterly through the Program Administrator or Authorised Signatory, and the rebate is paid to the company by demand draft or bank transfer.
Do reward points expire? Yes, two years from the date earned. No prior intimation is sent, though business card customers get an SMS five days before.
Can I withdraw cash? No. ATM withdrawal, call-a-draft, fund transfer and cash advance are all shown as NA.
What is the interest rate? 3.30% per month (39.60% per annum) on the corporate-liability variant. The individual-liability variant is 3.50% per month (42.00% per annum) with an additional ₹300 charge.
What happens if I exceed the credit limit? Nil on corporate-liability cards. ₹500 on individual-liability corporate cards.
Do the fuel and railway waivers always apply? No. The card page flags both as applicable only on the paid annual fee variant.
Fees, benefits and terms verified against the Kotak Corporate Platinum Credit Card product page, its fees-and-charges page, its FAQ page, the Kotak Corporate Credit Card MITC dated 30 March 2020 and Kotak's complimentary airport lounge access terms, as at 23 September 2026. The corporate MITC is six years older than the retail MITC used for Kotak's other cards, so some figures may have moved; the fees-and-charges page is the more current document and is preferred where they differ. The reward rate on this card is not published in any of these sources.
Cards Mentioned in This Article